Why Title Search Matters Before Buying Land
Table of Contents
- What a Title Search Reveals About Your Land
- Why Title Search Is Essential Before Closing
- Common Title Search Defects That Stop Deals
- Easements and Encumbrances on Vacant Land
- Title Insurance and Its Role in Protection
- Hiring a Professional Title Researcher vs. DIY Search
- Red Flags and Risks of Skipping Title Search
- Frequently Asked Questions
Last Updated: Sep 30, 2026
What a Title Search Reveals About Your Land
A title search is a detailed examination of public records to verify ownership history, uncover claims against the property, and identify restrictions or encumbrances. A title search buying land reveals the complete legal story of that property, who owned it before, whether anyone else has rights to it, and what conditions or limitations apply to your ownership.
A title researcher pulls documents from county records, court files, and tax assessments to build a chain of title, the ownership history traced backward through time. The researcher looks for gaps, irregularities, or red flags that might indicate a problem. This step is not optional; it's the foundation of a safe purchase.
A title search catches problems before closing day, liens, improperly discharged foreclosures, or easements, rather than after you've signed the deed. The importance of title search before buying land is critical because once you own the property, you're responsible for resolving whatever problems exist.
Key TakeawayA title search reveals ownership history, outstanding claims, liens, easements, and restrictions on your property. Without it, you could inherit legal disputes, financial obligations, or use restrictions you didn't anticipate.Why Title Search Is Essential Before Closing
Skipping a title search is one of the riskiest decisions a land buyer can make. The title search buying land protects you by uncovering problems that could cost thousands or make the property unsellable. Once the deed is in your name, the burden of fixing title issues falls entirely on you.
If a previous owner failed to pay property taxes, the county has a lien against the land. Buying without discovering this lien means you inherit the debt and risk foreclosure. A title search identifies tax liens before you close, giving you the chance to negotiate with the seller or walk away.
Judgment liens from lawsuits, mechanic's liens from unpaid contractors, and improperly discharged mortgage liens all show up in a title search and represent potential financial or legal liability. Professional title researchers know where to look and what documents to request to uncover these claims.
A thorough title search buying land also examines the chain of title for red flags: multiple ownership changes in a short period, gaps in the ownership record, or unresolved probate issues. These situations create a "cloud on title", legal uncertainty about whether the seller actually has the right to sell you the property, which a title search identifies before you commit your money.
Watch OutA missing or incomplete title search can result in inherited liens, foreclosure risk, or legal disputes that cost tens of thousands of dollars to resolve. Once you own the property, the responsibility is yours.Common Title Search Defects That Stop Deals
Liens and Tax Claims
A lien is a legal claim against your property as security for a debt. When you buy property with a lien attached, you're buying the debt along with the deed.
Tax liens are particularly common and take priority over your ownership claim, meaning the government can seize and sell the property to recover what's owed. A title search identifies every lien so you can negotiate with the seller to pay it off before closing or lower the purchase price to account for the debt.
Judgment liens appear when someone won a lawsuit against the previous owner. These liens cloud the title and make the property difficult to sell or refinance until they're satisfied.
Foreclosure History and Probate Issues
If the previous owner went through foreclosure, the title search reveals it. More importantly, if a foreclosure was initiated but not properly completed, the title can be clouded. A title researcher verifies that the foreclosure was completed correctly and the bank's interest was properly discharged.
Probate issues arise when a property owner dies. If probate was never opened or not properly closed, the title may be unclear and multiple heirs might claim rights to the property. A title search uncovers these probate gaps before you buy.
Pro TipAlways ask for a preliminary title report before closing. This document lists all title defects found during the search and gives you time to address them with the seller or your attorney.Easements and Encumbrances on Vacant Land
An easement is a right that someone else has to use part of your property, for example, a utility company running power lines or a neighbor using a road to reach their land. Easements are permanent and transfer with the property to every future owner.
On vacant land, easements are extremely common and critical to understand. A utility easement might prevent building in certain areas, a road easement affects privacy and access control, and a conservation easement might prohibit development entirely.
A title search reveals all easements and other encumbrances, liens, covenants, restrictions, and agreements that run with the land. This information is essential for evaluating whether the land suits your intended use before you close.
Restrictive covenants are rules or restrictions imposed by a previous owner or homeowners association that limit how you can use the property. These restrictions are legally binding and transfer to you with the property. A title search identifies them so you understand the limitations before buying.
Title Insurance and Its Role in Protection
Title insurance protects you against losses from title defects that existed before you bought the property but weren't discovered during the title search. Unlike homeowners insurance, it protects against past problems hidden in the chain of title or public records.
Lenders require a lender's title insurance policy to protect their investment. You can also purchase an owner's policy, a one-time premium paid at closing that covers you for as long as you own the property.
Title insurance doesn't replace a thorough title search. Instead, it works alongside the search. The title company conducts the search to identify and resolve problems before closing. Title insurance then covers you if a problem emerges later, for example, if a long-lost heir appears years later claiming rights to the property, or if a forged deed is discovered in the chain of title. The insurance company will defend you legally and pay damages up to the policy limit.
The importance of title search before buying land is reinforced by the role of title insurance. The search is the first line of defense; the insurance is your backup protection. Together, they create a comprehensive safety net that protects your ownership and your investment.
Hiring a Professional Title Researcher vs. DIY Search
Some buyers attempt to conduct their own title search to save money. Public records are accessible, and basic information is often available online. However, DIY title searching is risky for several reasons.
A professional title researcher has training, experience, and access to specialized databases and records that aren't available to the general public. They know which documents to request, where to find them, and how to interpret them. They understand the legal language in deeds, mortgages, and court documents. They know how to spot red flags, unusual patterns, gaps in the ownership record, or inconsistencies that suggest a problem. They also know the specific requirements and quirks of each county's record-keeping system.
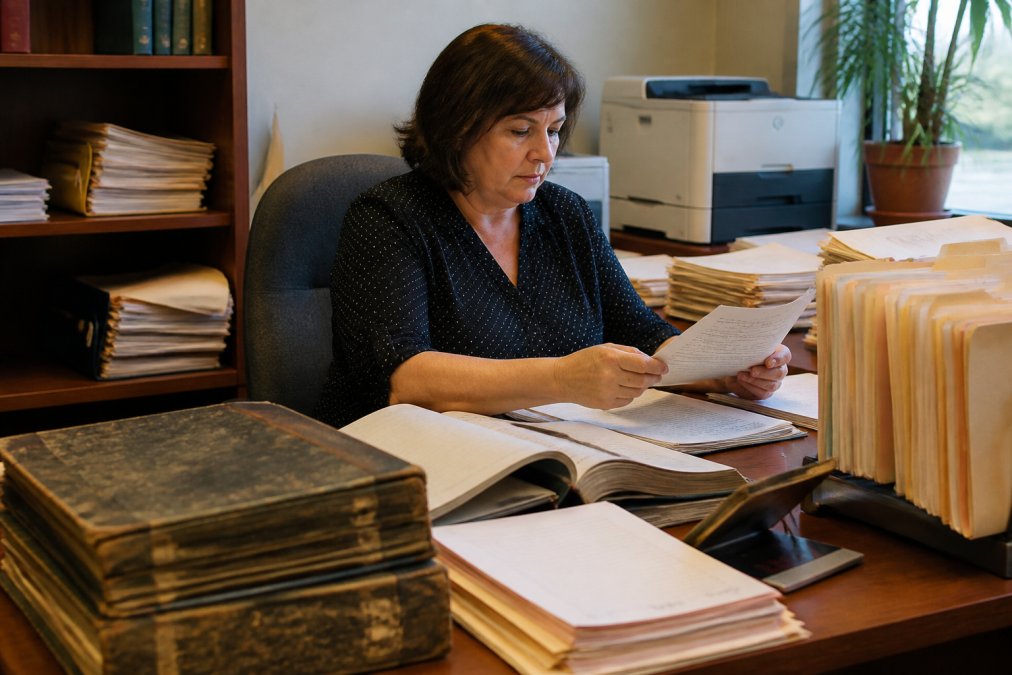
Professional real estate title researcher reviewing property documents and public records at a desk with multiple file folders, county record books, and a computer screen displaying land parcel information
A DIY search often misses critical documents or misinterprets what they mean. You might find the most recent deed but miss a lien filed in a different county or a judgment against the previous owner that appears in civil court records rather than property records. You might see an easement but not understand its implications for your intended use of the land. The cost of correcting a missed problem after closing, or the loss of your investment if the problem is severe, far exceeds the cost of hiring a professional.
Professional title researchers and title companies offer another advantage: they carry errors and omissions insurance (ALTA). If they miss something and you suffer a loss, you have recourse. A DIY search offers no such protection. When you conduct your own search, you're entirely responsible if you miss something.
For the importance of title search before buying land to translate into actual protection, hire a professional. The cost is modest compared to the purchase price and the risk.
Red Flags and Risks of Skipping Title Search
The most obvious risk of skipping a title search is buying a property with hidden liabilities. You could inherit liens, back taxes, or legal claims that cost thousands to resolve. But the risks go deeper.
Watch OutBuying land without a title search is gambling with your investment. Once you own the property, you're responsible for all problems, past and present. A title search is the only way to identify and address problems before closing.Frequently Asked Questions
Can I perform a title search myself, or should I hire a professional title researcher?
You can access public records yourself through county assessor and courthouse databases, but a professional title researcher brings expertise in interpreting complex ownership chains, identifying hidden defects, and spotting legal issues you might miss. DIY searches work for straightforward properties, but raw land often has complications, mineral rights, old easements, or unclear conveyances, that require trained eyes. Many buyers hire a professional to avoid costly post-closing disputes.
What are the most common red flags found during a title search on vacant land?
Watch for tax liens, judgment liens against previous owners, unclear chain of title with missing deeds, easements that restrict your use, restrictive covenants limiting development, foreclosure history, probate issues, and survey discrepancies. Encroachments from neighboring properties and mineral rights claims are also frequent on raw land. Any gap in the ownership chain or unresolved legal claims can block financing and create liability after closing.
Is a title search legally required when purchasing vacant land?
Title search is not legally mandated, but lenders require it before approving a mortgage. If you're paying cash, you're not legally required to search, but skipping it exposes you to significant financial and legal risk. Undiscovered liens, ownership disputes, or restrictive covenants can surface years later, forcing expensive litigation or preventing resale. Professional title insurance, which requires a title search, protects against these post-closing losses.
What is the difference between a title search and title insurance?
A title search is the investigation process, a thorough examination of public records to verify ownership and identify defects. Title insurance is protection: a one-time policy that covers you if problems emerge after closing. The search uncovers known issues; insurance protects against unknown ones missed during the search. Most buyers get both: the search identifies defects to resolve before closing, and insurance covers residual risk.
0 Comments